

Mortgage advice in Schiedam
The independent mortgage advisor in Schiedam who really thinks along
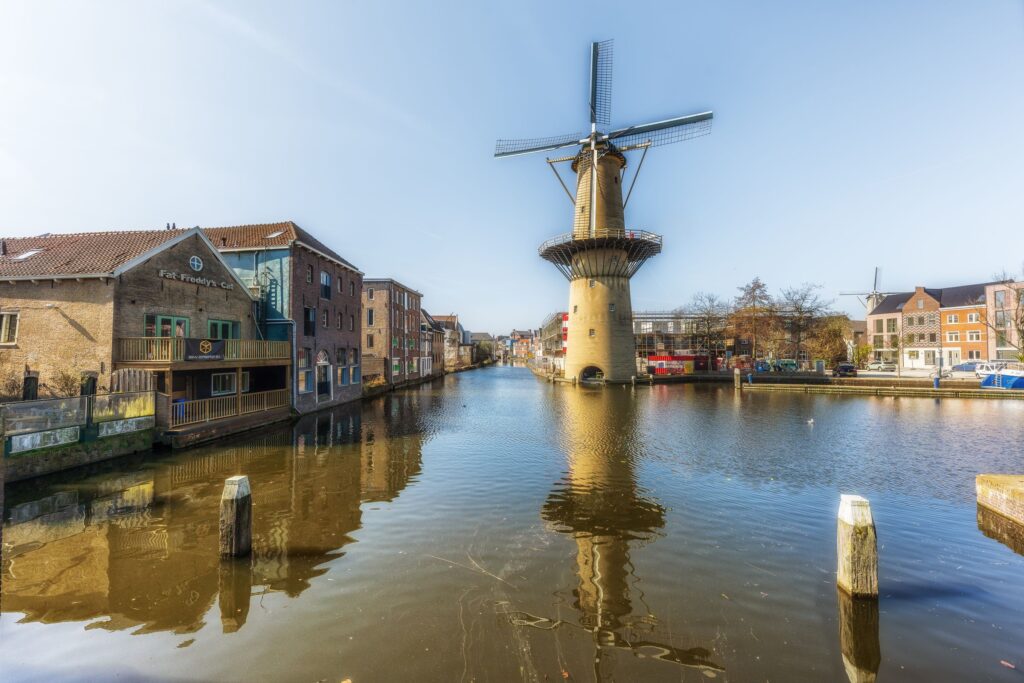
Schiedam is in demand. You live a stone’s throw from Rotterdam, but often get more space for your money. That is why more and more first-time buyers and movers from Rotterdam are looking this way.
The housing supply is varied: characterful buildings along the canals in the city centre, walk-up apartments in Nieuwland and Oost, and spacious family homes in Groenoord and Woudhoek. These differences matter for your mortgage. An old building in the city centre needs different attention than a family home from the 1980s, for example when it comes to the foundation, the energy label and possible sustainability costs.
We look beyond your maximum loan amount. We look at who you are, what you want and the house you have your eye on. That way you get a mortgage that truly suits you.
Good
to know
Taking out a mortgage for a home in Schiedam involves quite a lot. Here you will find information you can use during the buying process.
Many homes in the old centre of Schiedam date from around 1900 or earlier. For these buildings, a structural survey is extra important, and sometimes a foundation inspection as well. Defects can affect the valuation and therefore how much you can borrow. We discuss this with you beforehand, so you know where you stand before you make an offer.
Yes. For a home with a lower energy label, you can often borrow extra for energy-saving measures such as insulation, solar panels or a heat pump. This is interesting for many older homes in Schiedam. Together we calculate what is possible and whether it pays off financially.
Absolutely. We work throughout the Rotterdam region, including Schiedam, Vlaardingen and the surrounding area. You have the same advisor from start to finish. We can meet online, at our office or at your home, whatever suits you best.
When choosing a mortgage, it is not just about interest and monthly payments. The type of mortgage determines how you repay, how much security you have, and what your financial future looks like. In the Netherlands, there are three popular mortgage types that almost everyone considers: annuity mortgage, linear mortgage, and (partially) interest-only mortgage. In this article, you will find more information about the different mortgage types.
An energy label shows how energy-efficient a home is. This is not only important for the environment and the comfort you can expect, but also for your maximum mortgage. In most cases, an energy label is mandatory.
Your mortgage advisor in Schiedam
We are fully independent, and you decide the direction. With us you always deal with the same advisor, instead of having to tell your story again to a new face each time. Have your eye on a house in Schiedam? Then we act quickly. With the Bid Guarantee by Jord you can make an offer without a financing condition and stand stronger against other buyers. Whether you are buying for the first time, have just moved to the Netherlands as an expat, are an entrepreneur or have taken out a mortgage before.
Rates
We work with fixed rates for our mortgage advice. This way, you will never be faced with any surprises.
Starter
-
Advice for your first home purchase
Mover
-
Advice for your next home purchase
Entrepreneur
From
-
Advice for your situation at standard rates plus a surcharge. Please note: the surcharge is a starting price based on the complexity of the business
Key terms and mortgage types
Interest-only mortgage
Linear Mortgage
Annuity Mortgage
Mortgage Application
Buyer’s costs (k.k)
Clear and personal mortgage advice
We have already made over 2,000 customers happy.

How our mortgage advice
in Schiedam works
Introduction & free mortgage consultation
The financial check
Looking for a suitable house
The mortgage application
The mortgage is finalized, off to the notary
How can we help you?
Schedule a free mortgage consultation or ask your question. We will contact you as soon as possible!
Our knowledge of buying a house
In our articles, we share practical explanations, current developments, and answers to frequently asked questions about mortgages.
How much can I borrow in 2026?
It is one of the most frequently asked questions. In this blog, you can read more about determining the maximum mortgage